Background

 Strategic Funding Advisor

 Firm Expertise

 Practical Experience

 Legendary Customer Service

 Closed Deals

 Testimonials

 Business Funding

 Acquisition Funding

 Mezzanine Funding

 Advisory

 Mezzanine Funding

 Mezzanine Expertise

 Mezzanine Tools

 Acquisition Funding

 Acquisition Funding Expertise

 Advisory

 Case Studies
Attract Capital closed over $200 million of funding volume in 2025 across a variety of deal types including acquisition financings, refinancings and leveraged recapitalizations. A sampling of closed deals ranged from mezzanine unitranche loans to senior secured loans is presented below. Delayed draw term loans were a material part of the overall structure of the mezzanine unitranche loans.
A unitranche loan combines what would otherwise be separate senior and subordinated loans into one loan, with one blended interest rate and one lender, instead of the company negotiating with two or more separate lenders.
For a closer look at how these loans are structured, see Attract Capital’s mezzanine debt financing services.
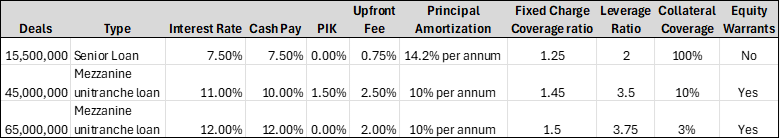
Our subset of three closed deals is comprised of direct lending transactions with founder-owned companies without a private equity backer. Both of these deals had unique aspects which required a collaborative lender approach to close. The terms for each deal vary but are within a general market range in terms of pricing, leverage ratio and covenants. The quotes interest rate for senior secured deal was 7.5% reflecting its 100% collateral coverage position. Covenants are performance tests set to gauge the health of the business. Usually there are two including debt service coverage ratio and leverage ratio
Collateral coverage refers to how much of the loan is backed by the company’s hard assets, such as equipment, inventory and receivables. A 100% collateral coverage position means the loan is fully secured by those assets, which is a key reason the senior secured loan carries the lowest interest rate of the two.
The fixed charge coverage ratio and leverage ratio was 1.25 times and 2.0 times respectively for the senior secured loan. The quoted interest rates for the first dollar, mezzanine unitranche loans ranged from 11.0% to 12.0%. Payment in kind interest option was quoted of 1.5%. PIK is payment in kind which means it is not paid in cash but accrued and the cash payment is deferred. These two deals had negligible collateral coverage, 10% and 3% respectively, characteristic of a cash flow structured loan. The fixed charge coverage ratio range of 1.45 to 1.50 and the leverage ratio range of 3.5 times to 3.75 times EBITDA. EBITDA is the way cash flow is measured in leveraged financing and it drives the amount and pricing of the funding.
For comparison, here is how the two loan types stacked up side by side:.
| Term | Senior Secured Loan | Mezzanine Unitranche Loan |
| Interest rate | 7.50% | 11.5% to 12.0% cash pay, plus 1.5% PIK |
| Collateral coverage | 100% | 10% and 3% (negligible — cash flow structured) |
| Fixed charge coverage ratio | 1.25x | 1.45x to 1.50x |
| Leverage ratio | 2.0x EBITDA | 3.5x to 3.75x EBITDA |
| Upfront closing fee | 0.75% | 2.0% to 2.5% |
| Prepayment fee (refinancing) | Not separately quoted | 3% in year 1, sunsetting to 2% by year 3 |
The mezzanine unitranche lender is a direct lender who functions as a one-stop provider of capital. These deals bring greater processing efficiency and follow-on capital support. These deals require extensive due diligence but are able to close faster due to the lack of multiple lenders and multiple legal teams that cause delays in intercreditor negotiation. Upfront closing fees ranged from 2.0% to 2.5% for the mezzanine unitranche loan and prepayment fees for refinancing were 3% in year one sunsetting to 2% in year 3. Principal amortization in year 1 through 4 averaged 10% with 60% of the principal repaid at maturity. Amortization means the percentage of the outstanding principal expected to be repaid each year. 10% amortization means 10% of the outstanding principal will be repaid in a given year.
Intercreditor negotiation is the back-and-forth between multiple lenders over who gets repaid first and under what conditions if something goes wrong. With a single direct lender providing the entire capital stack, there is no separate intercreditor agreement to negotiate, which is a key reason these deals were able to close faster.
Delayed draw term loan sizes averaged from 1.0 to 2.6 times the initial term loan drawn at closing. For example, the mezzanine unitranche loan of $75 million was an extension of an initial loan amount of $29 million, provided to fund a continuous roll-up strategy. The $55 million mezzanine unitranche loan had an accordion delayed draw term loan in the amount of $50 million to support future acquisition growth. The tailored use of delayed draw term loans creates structured loan availability to support follow-on acquisition funding for both platforms, enabling them to scale efficiently and rapidly. The level of total delayed draw term commitment creates a large incentive for future growth and results in the lender justifying an equity warrant.
An accordion feature is a pre-negotiated option built into the loan agreement that lets the company borrow additional money later, on already-agreed terms, without renegotiating the entire loan agreement. It works in a similar way to a delayed draw term loan.
If you are evaluating financing for an acquisition, refinancing or recapitalization, reach out through our contact form and we can walk through what a similar structure could look like for your business.