Background

 Strategic Funding Advisor

 Firm Expertise

 Practical Experience

 Legendary Customer Service

 Closed Deals

 Testimonials

 Business Funding

 Acquisition Funding

 Mezzanine Funding

 Advisory

 Mezzanine Funding

 Mezzanine Expertise

 Mezzanine Tools

 Acquisition Funding

 Acquisition Funding Expertise

 Advisory

 Case Studies
Acquisition financing should only require a personal guarantee under a very narrow set of circumstances. Often when buyers get desperate to raise acquisition financing, they feel that a personal guarantee is the only way forward.
This view springs from experience with banks and the SBA program. When banks are providing acquisition financing and the deal is not backed by a private equity fund, they ask for a personal guarantee to mitigate credit risk. This is understandable as banks lend at razor thin margins and have little room for loss.
The SBA program also requires personal guarantees and a very onerous form of guarantee at that. However, private credit funds and mezzanine funds are outside the banking market, with a credit mentality based on higher risk and higher reward.
Personal Guarantees in Acquisition Financing
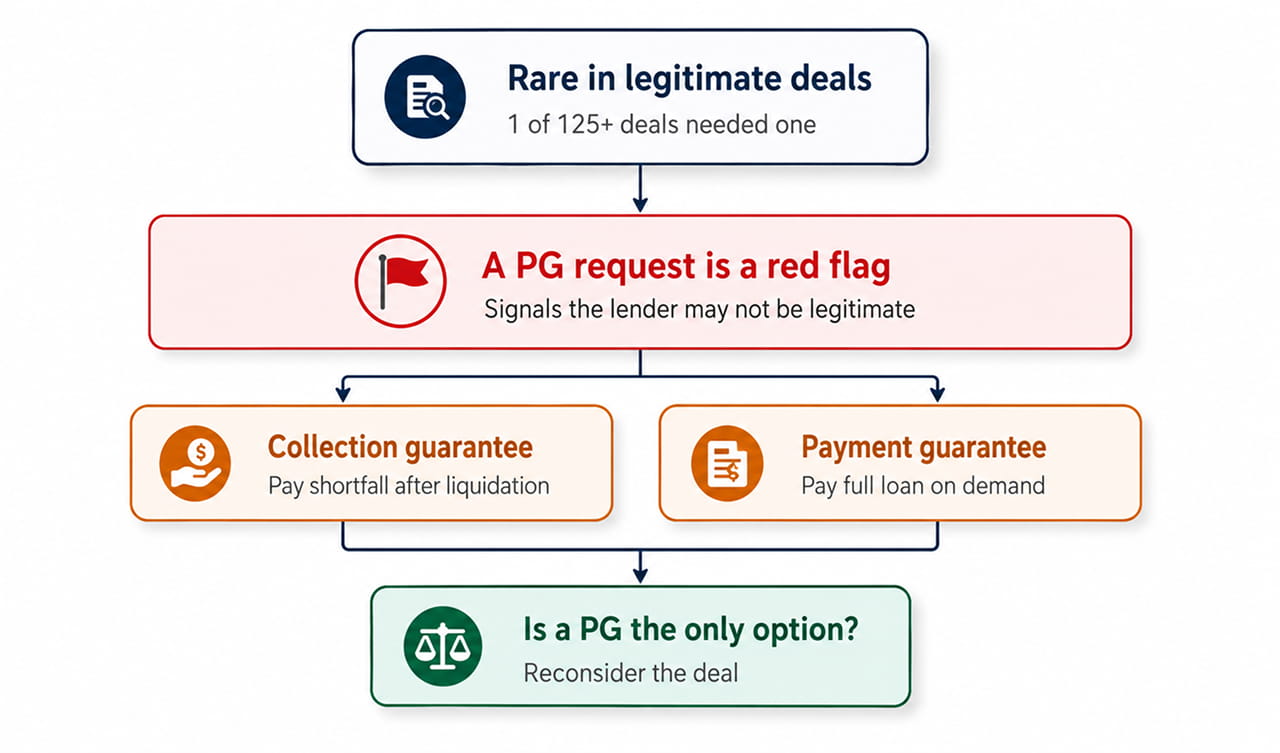
These types of acquisition financing providers rarely ask for personal guarantees aside from very specific circumstances. In the past 35 years, we have been involved in over 125 private credit-based financings and only one deal needed a personal guarantee due to its preponderance of cash inventory.
So term sheets that call for a personal guarantee from a non-bank lender should be approached warily. Usually, when this shows up in a term sheet, it is a sign that the lender is not legitimate or does not have the capital they purport to lend.
They are loan originators who sign up a buyer and then go out and raise the acquisition financing on a one-off basis from other capital providers. The guarantees can be punitive, and many are misunderstood as to the underlying obligation they create.
The two most common forms are payment guarantees and collection guarantees. A collection guarantee means the lender can come to the buyer after having liquidated all assets and make the buyer pay the collection shortfall.
The payment guarantee is where the lender can force the buyer to pay them the full amount of the loan at any time, regardless of how much they have already collected. Payment guarantees are very onerous to live with as a buyer as they create tension and have the potential to destabilize the business, regardless of the underlying performance.
Buyers should be aware of what is market for each type of acquisition financing loan they are raising. If the personal guarantee is the only way forward, you should reconsider your direction.